 Following today’s release of John Lewis & Partner’s figures for the H1 ending 1 August 2026; Zoe Mills, head of UK retail at GlobalData, a leading intelligence and productivity platform, offers her view: “John Lewis & Partners has failed to maintain the momentum it established in FY2025/26 – its first return to annual sales growth in four years – and has reported a decrease in revenues in H1 2026/27, with a second consecutive year of annual growth now likely to be out of reach. Outgoing Managing Director, Peter Ruis, has made a significant impact on the retailer’s operations and likely would have preferred to leave when the results reflected this impact positively. The department store retailer’s sales in the first half fell by 2.4%, impacted by a challenging economic environment, ongoing inflation, and its midmarket-plus pricing, deterring cautious consumers. John Lewis & Partners was already operating at a loss in H1 FY2025/26, reporting a £53m deficit in the first half of the year; this situation has worsened, resulting in an £83m loss for the first half of this year, due to weaker sales results, investment in its store estate and margin pressures.
“Ruis’ reintroduction of Never Knowingly Undersold (NKU) in 2024 significantly boosted performance in H1 2025/26. However, the initial halo effect this drove has annualised out, and this price promise was not enough to bolster footfall in H1 2026/27. Its home division performed better than other areas, down 2.8% in the first half, with it the least likely to be impacted by NKU given its strong own-brand offer. In contrast, technology sales decreased by 3.7%, even with the launch of Apple’s MacBook Neo during this period. Amid tighter budgets, even the introduction of more entry-level products has not encouraged shoppers to replace items before they break.
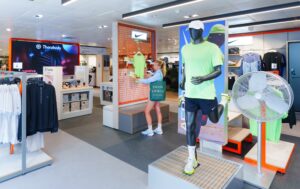
“Fashion was John Lewis & Partners’ weakest segment by some margin, with sales down 4.8%. However, the clothing & footwear market has been among the worst-performing in the UK for several years, and the department store chain has not been immune to this. Investing in Sports and Wellness is a clear strategy to address weak performance. If the concept that has recently been displayed on Oxford Street is expanded beyond the three known locations, it could increase demand in a competitive sports market, especially since few other retailers provide such a wide variety of brands under one roof.”